- Free Consultation: (907) 277-3090 Tap Here to Call Us

U/UIM Protects Alaskans


U/UIM Protects Alaskans – Imagine you are in a motor vehicle accident. You are working through a recovery, have a damaged vehicle and need to replace your lost wages. Upon contacting the insurance provider to make a claim for your losses, you discover the driver who struck you either doesn’t have enough insurance or no insurance at all. Later, you realize the other driver is unable to reimburse you the settlement amount needed to put you back on the playing field.
U/UIM Protects Alaskans In These Situations
You can purchase uninsured motorist (U) / underinsured motorist (UIM) coverage from your insurance provider. Although they cover different events, these two coverages are normally sold together as a package. U/UIM Protects Alaskans. These coverages are in addition to your liability coverage or Medical Payments coverage.
What Does U/UIM Cover?
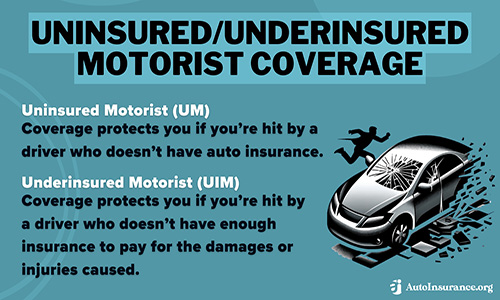
U/UIM Protects Alaskans – it covers bills resulting from injuries or damages caused by a driver who didn’t have enough or any insurance coverage. Uninsured motorist insurance covers accidents caused by both hit-and-run drivers and drivers without coverage. Underinsured motorist insurance covers injuries and damages resulting from an accident caused by a driver who doesn’t have enough to cover all claims.
Alaskan Insurance Companies Must Offer U/UIM Coverage
Although Alaska law does not require drivers to purchase U/UIM coverage, it requires insurance companies to offer this protection. This requirement falls under Alaska Statute 28.22.201.
Insurers must offer U/UIM limits that are at least equal to your liability policy limits. They must also offer optional higher limits. While insurance companies must offer U/UIM coverage, Alaskans have the option to decline or lower U/UIM coverage by signing a specific form.
Critical Notes On Uninsured / Underinsured Motorist Coverage
REMEMBER: U/UIM Protects Alaskans – If you choose not to sign a rejection or selection form, Alaska law requires the insurance company to include U/UIM coverage in your policy at limits that match your liability coverage. Your insurance provider will automatically added this coverage to your policy, unless you refuse. If you refuse the coverage, you must do so in writing.
Alaska requires drivers to carry minimum liability insurance of $50,000 per person and $100,000 per accident for bodily injury, plus $25,000 for property damage. However, an auto accident can result in damages that exceed these coverage limits. Alaskans who decline uninsured/underinsured motorist (U/UIM) coverage must acknowledge the potential financial risks. Without this coverage, they may not receive full compensation after a crash involving an uninsured or underinsured driver. U/UIM protects Alaskans.
Most importantly, U/UIM coverage is not automatically included in your policy; you must specifically request it. Once you reject the coverage, it’s excluded in any renewals unless you later request U/UIM in writing.
U/UIM Protects Alaskans and can be crucial in these situations, especially given that many drivers in Alaska and nationwide are uninsured or underinsured.
Understanding Auto Insurance Stacking in Alaska
If you are in an accident, it is important to gather as much information as possible from the other driver. Ask for registration in addition to proof of insurance. In many cases, several insurance policies can apply to assist in making injured parties whole following a crash. Alaska law limits the ability to stack uninsured and underinsured motorist (UM/UIM) coverage, but drivers may qualify for coverage under multiple insurance policies in certain circumstances.
Johnson Law has been helping Alaskans for nearly 30 years. It’s who we are. Call Johnson Law at (907)277-3090 or use our Contact Form to discuss your Alaska accident injury case. We are here to serve you.
And while we hope you never need us… We’re here if you do. ~ Doug Johnson
Source: Safe Motorist: Alaska Safe Motorist Guide; Alaska Statute 28.22.201.
Image Source: Auto Insurance
Disclaimer: This article, U/UIM Protects Alaskans, provides general Alaska insurance information. However, it is not intended as legal advice. Laws and regulations may change, and how they apply depends on the specific facts of each situation. Reading this article or contacting Johnson Law, P.C. through this website does not create an attorney-client relationship. If you have questions about a personal injury matter, automobile accident, or your legal rights, consult an attorney about your specific circumstances.